

 弊社は製品に自信を持っており、面倒な製品を提供していません。


PDF版の多くの利点
我々のREG本当質問のPDF版を選択したら、あなたは無料デモをダウンロードして購入前の試用サービスを楽しみます。こうしたら、あなたは弊社のREG CPA Regulation資格問題集をより了解して、買うかどうかを決定します。さらに、我々のREGオンライン練習資料のPDF版は印刷できるので、あなたは重要な知識点の下にアンダーラインをつけます。復習のときに、マークされたところをスキャンしてもいいだけです。それはあなたのために大量の時間を節約するだけでなく、学習効率を向上させます
失敗した後に、再びやってみるのを恐れることがあります。しかし、高品質で有効な資格問題集の助けにより、あなたは試験の失敗を恐れる必要がありません。我々のREG CPA Regulation試験問題集参考書を使用するのをお勧めします。我々の試験勉強資料を選んで、あなたはとても良いポイントを得ることができます。我々のREG本当の質問のメリットは以下のように表示されます。
20~30時間の練習は試験に十分です
試験に合格するには数ヵ月ないし数年かかることもありますが、弊社のREGCPA Regulation試験問題集で試験に簡単に合格するには、20時間または30時間しかかかりません。今には、我々のREG本当の質問の指導の下で、あなたは自分でそのように体験することができます。机の前に座って全日に来る試験の準備をしなくて、あなたは暇のときに、我々のREG最新問題集をスキャンして本当の試験にテストされるキーポイントを把握できます。その結果、同じ難易度の質問になると、我々のREG CPA Regulation練習資料を使用しない他の人が費やした合計時間の四分の一が必要になることがあります。
購入前の試用体験
別の試験練習資料に比べて、我々のREGCPA Regulation資格問題集はあなたに購入前の試用サービスを提供します。あなたは必要とする試験ファイルをより解させます。我々のREGトレーニング資料は購入前のチェックを受けることが自信を持っているのは高品質で選択できる三つの異なるバージョンがあるだけでなく、あらゆる階層の人々に適しているからです。また、試用サービスを楽しんだほとんどの人は我々の試験ファイルを最も有効な勉強資料として、REG CPA Regulation練習資料を購入しました。
AICPA REG 試験シラバストピック:
| セクション | 比重 | 目標 |
|---|---|---|
| 事業体に対する連邦課税 | 28~38% | - 会計上の利益と課税所得の差異及び配当等の分配 - S法人 - パートナーシップ及び有限責任会社(LLC) - C法人 - 非課税団体 |
| 倫理、職業上の責任、連邦税務手続き | 10~20% | - 米国財務省通達230号に定められた規則 - IRSによる監査、不服申立て、徴収手続き - 資格認定と懲戒制度 - 税務業務における倫理と責任 - 税務申告者に対する罰則と注意義務 |
| 個人に対する連邦課税 | 15~25% | - 損失の控除限度額及び税額の計算 - 申告区分と所得控除 - パススルー事業体からの所得の申告 - 所得調整項目、所得控除及び税額控除 - 総所得に算入される項目及び除外される項目 |
| 資産取引に関する連邦課税 | 12~22% | - 資本資産と通常資産の区分 - 資産の取得原価基準と保有期間 - 利益及び損失の認識 - 同種資産交換及び強制的な資産処分による交換 - 原価回収、減価償却及び償却 |
| ビジネス法 | 10~20% | - 代理権に関する法律関係 - 契約法及び統一商法典第2編 - 担保取引(統一商法典第9編) - 債権者・債務者の関係及び倒産手続き - 事業体の法的形態と枠組み |
AICPA CPA Regulation 認定 REG 試験問題:
Allen owns 100 shares of Prime Corp., a publicly-traded company, which Allen purchased on January 1,
2 001, for $10,000. On January 1, 2003, Prime declared a 2-for-1 stock split when the fair market value
(FMV) of the stock was $120 per share. Immediately following the split, the FMV of Prime stock was $62
per share. On February 1, 2003, Allen had his broker specifically sell the 100 shares of Prime stock
received in the split when the FMV of the stock was $65 per share. What amount should Allen recognize
as long-term capital gain income on his Form 1040, U.S. Individual Income Tax Return, for 2003?
- A. $2,000
- B. $750
- C. $1,500
- D. $300
解説: (Tech4Exam メンバーにのみ表示されます)
Freeman, a single individual, reported the following income in the current year:
Guaranteed payment from services rendered to a partnership $50,000
Ordinary income from a S corporation $20,000
What amount of Freeman's income is subject to self-employment tax?
- A. $70,000
- B. $0
- C. $50,000
- D. $20,000
解説: (Tech4Exam メンバーにのみ表示されます)
In the current year Jensen had the following items: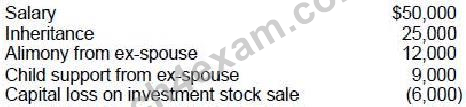
What is Jensen's AGI for the current year?
- A. $59,000
- B. $62,000
- C. $84,000
- D. $44,000
解説: (Tech4Exam メンバーにのみ表示されます)
Cobb, an unmarried individual, had an adjusted gross income of $200,000 in 1990 before any IRA
deduction, taxable social security benefits, or passive activity losses. Cobb incurred a loss of $30,000 in
1 990 from rental real estate in which he actively participated. What amount of loss attributable to this
rental real estate can be used in 1990 as an offset against income from nonpassive sources?
- A. $12,500
- B. $25,000
- C. $0
- D. $30,000
解説: (Tech4Exam メンバーにのみ表示されます)
Hall, a divorced person and custodian of her 12-year old child, filed her 1990 federal income tax return as
head of a household. She submitted the following information to the CPA who prepared her 1990 return:
. The divorce agreement, executed in 1983, provides for Hall to receive $3,000 per month, of which $600
is designated as child support. After the child reaches 18, the monthly payments are to be reduced to
$ 2,400 and are to continue until remarriage or death. However, for the year 1990, Hall received a total of
only $5,000 from her former husband. Hall paid an attorney $2,000 in 1990 in a suit to collect the alimony
owed.
. In June 1990, Hall's mother gifted her 100 shares of a listed stock. The donor's basis for this stock, which
she bought in 1970, was $4,000, and market value on the date of the gift was $3,000. Hall sold this stock
in July 1990 for $3,500. The donor paid no gift tax.
. During 1990, Hall spent a total of $1,000 for state lottery tickets. Her lottery winnings in 1990 totaled
$ 200.
. Hall earned a salary of $25,000 in 1990. Hall was not covered by any type of retirement plan, but
contributed $2,000 to an IRA in 1990.
. In 1990, Hall sold an antique that she bought in 1980 to display in her home. Hall paid $800 for the
antique and sold it for $1,400, using the proceeds to pay a court-ordered judgment.
. Hall paid the following expenses in 1990 pertaining to the home that she owns: realty taxes, $3,400;
mortgage interest, $7,000; casualty insurance, $490; assessment by city for construction of a sewer
system, $910; interest of $1,000 on a personal, unsecured bank loan, the proceeds of which were used
for home improvements. Hall does not rent out any portion of the home.
What amount should be reported in Hall's 1990 return as alimony income?
- A. $36,000
- B. $5,000
- C. $28,800
- D. $0
解説: (Tech4Exam メンバーにのみ表示されます)

 田村**


